


Page 16 - Rare Earths and Rare Materials
P. 16
MITIGATING          FUTURE          CONFLICTS:    projects, promoting recycling initiatives and investing
            INTERNATIONAL          COOPERATION         AND    in alternative sources of REEs can reduce these
            INITIATIVES                                       vulnerabilities and ensure a more stable supply of
            While the potential for future conflicts over REEs  critical materials.
            and critical materials is significant, there are several  The first step towards diversification is the
            strategies that nations can pursue to mitigate these  development of new mining projects in previously
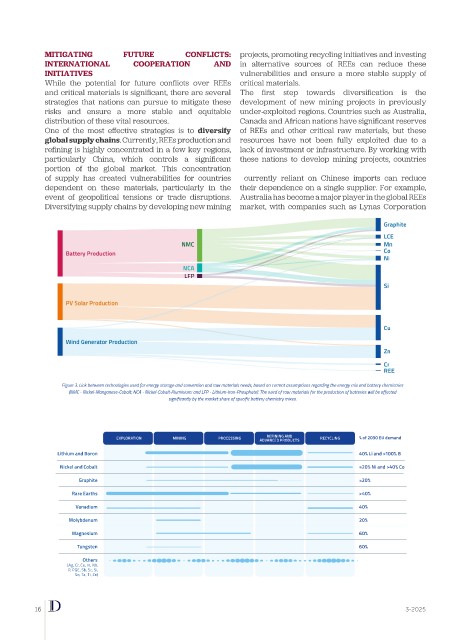
                Besides highlighting the forecasted EU demand in 2030 relative to current production, the figure shows that the
            risks and ensure a more stable and equitable  under-exploited regions. Countries such as Australia,       Access to raw materials and EU strategic partnerships
                ERMA cases identified to date can supply a very significant proportion of the EU demand. The values reported
            distribution of these vital resources.            Canada and African nations have significant reserves    In recent times, raw materials have forcefully come to the attention of the public and policymakers. There is now
                in Figure 2 are based on the current assumptions in terms of relative proportions of energy sources and battery
            One of the most effective strategies is to  diversify  of REEs and other critical raw materials, but these   an increased awareness of the risks associated with potential disruptions in the supply chains that underpin the
            global supply chains. Currently, REEs production and  resources have  not been fully exploited  due to a   EU’s economic prosperity, social stability and safety.
                types, as outlined in Figure 3. Figure 4 further shows that ERMA investments are distributed not only across Eu-
            refining is highly concentrated in a few key regions,  lack of investment or infrastructure. By working with
                rope and among different materials, but also, most importantly, across value chains. This is in line with ERMA’s
            particularly  China,  which  controls  a significant  these  nations  to  develop  mining  projects,  countries
                strategy to build up capacity and skills across all stages of the value chain, from exploration to mining, process-
            portion of the global market. This concentration                                                          While it is true that significant capacity exists within the EU, international partnerships need to be further de-
                ing, manufacturing and recycling. More investment cases will be submitted to ERMA in the coming months and
            of supply has created vulnerabilities for countries   currently reliant on Chinese imports can reduce     veloped to ensure diversification of supply and to address short-term as well as long-term gaps for some ma-
                years, potentially increasing the overall materials for energy storage and conversion production and recycling
            dependent  on  these  materials,  particularly  in  the  their dependence on a single supplier. For example,   terials. International partnerships need to be developed in harmony and synergy with the support provided by
                capacity in Europe across the various CRMs value chains.
            event of geopolitical tensions or trade disruptions.  Australia has become a major player in the global REEs   the EU and Member States to develop domestic resources. In this context, ERMA is multiplying its international
            Diversifying supply chains by developing new mining  market, with companies such as Lynas Corporation     strategic partnerships and outreach activities, both in terms of membership and in the leadership of investment
                                                                                                                      cases (Figure 5). In line with the European Commission’s outreach strategy, ERMA is a key player in the part-
                                                                                                  Graphite            nership with Canada and has been a driving force in the Memorandum of Understanding between the European
                                                                                                  LCE                 Union and Ukraine on a Strategic Partnership on Raw Materials. Other non-EU countries of strategic relevance
                                               NMC                                                Mn                  for ERMA include Kazakhstan and Namibia, and several countries with partnerships in the pipeline (Greenland
                  Battery Production                                                              Co
                                                                                                  Ni                  and Norway) or already announced (Argentina, Australia, Chile, Democratic Republic of Congo and Rwanda).
                                               NCA
                                                LFP                                                                   Besides its industry support for individual investment cases, ERMA is assisting the European Commission with
                                                                                                  Si                  the identification of emerging technologies and research topics that will restore the EU’s know-how and inno-
                                                                                                                      vation capacity. These include, among others, exploration, mining, processing, and recycling of materials used in
                  PV Solar Production
                                                                                                                      solar energy, wind energy and hydrogen-related technologies.

                                                                                                  Cu
                  Wind Generator Production
                                                                                                  Zn
                                                                                                  Cr
                                                                                                  REE
                 Figure 3. Link between technologies used for energy storage and conversion and raw materials needs, based on current assumptions regarding the energy mix and battery chemistries
                  (NMC - Nickel-Manganese-Cobalt; NCA - Nickel-Cobalt-Aluminium: and LFP - Lithium-Iron-Phosphate). The need of raw materials for the production of batteries will be affected
                                            significantly by the market share of specific battery chemistry mixes.
                                                                                                                                                               Greenland


                                                                    REFINING AND
                              EXPLORATION    MINING     PROCESSING  ADVANCED PRODUCTS  RECYCLING  % of 2030 EU demand                                      Norway                Kazakhstan
                Lithium and Boron                                                           40% Li and >100% B            Canada                               Ukraine
                Nickel and Cobalt                                                           ≈20% Ni and >40% Co
                     Graphite                                                               ≈20%
                   Rare Earths                                                              >40%
                                                                                                                                                               DRC          Rwanda
                    Vanadium                                                                40%
                                                                                                                                                             Namibia
                  Molybdenum                                                                20%                                                                                  Australia
                   Magnesium                                                                60%                                             Chile
                                                                                                                                                      Argentina
                     Tungsten                                                               60%
                      Others                                                                                                                Partnerships Signed  Partnerships in the pipeline  Partnerships Announced
                  (Ag, Cr, Cu, In, Nb,
                  P, PGE, Sb, Sc, Si,
                    Sn, Ta, Ti, Zn)
                         Figure 4. High-level view of the distribution of ERMA investment cases for a selected group of critical and strategic materials across the value chains.  Figure 5. Current and future EU-International strategic partnerships in the raw materials sector. Source: European Commission.
                                        The size of the bars is proportional to the investment needed for the various projects.
          16    16                                                                                     3-2025                                                                                               17

